


News:
Brokerage
Posted: June 23, 2008
Utilizing an internal rate of return (IRR) as an alternative analyzing tool
The most important alternative to net present value (NPV) is the internal rate of return (IRR) for evaluating an investment. These two methods of analysis are closely related in that; the IRR on an investment is the required return that results in a zero NPV when the NPV is used as the discount rate. Based on the IRR rule, an investment is acceptable if the IRR exceeds the required return.
The NPV and IRR will always lead to identical decisions as long as two conditions are met. First, the project's cash flows must be conventional, meaning that the first cash flow (initial investment) is negative and all the rest are positive. Second, the decision must be independent, meaning that the decision on accepting or rejecting a project does not affect the decision to accept or reject any other project.
Suppose you are considering an investment that has a total up-front cost of $ 435,440. The cash flows per year are as follows: Year one $100,000, Year two $200,000 and Year three $300,000. What is the IRR? If we require an 18% return, should we take this investment? First we see that at a 0% discount rate we have NPV of $164,560 ($600,000-435,440). To determine if we should pursue this investment we must discount the future cash flows at a discount rate that results in a NPV of 0.00. Therefore, in the example above, using a 15% discount rate, we would have NPV of 0.00 ($435,440-$86,960-$151,230-$197,250). Since we require an 18% return, we would reject this investment.
One might conclude that by investing $435,440 and realizing a return of $164,560 after three years is still a great investment. However, when doing any analysis, especially IRR, the rate of return an investor requires must be respected. Knowing the rate of return an investor requires allows a commercial real estate agent to focus only on properties that meet those criteria. Certainly, other factors will enter into the equation of whether or not to invest in a particular property; such as condition, location, quality of tenants and lease terms; but if the numbers make sense and the IRR meets the requirements of an investor, you are well on your way to providing sound advice to your client.
Knowing different analysis techniques and providing different analytical comparisons to an investor will assist in their decision making process. For more information on analyzing investment property consult a commercial real estate professional.
Gregory Oehler, MBA, is chief operating officer at Hunt Commercial Real Estate, Rochester, N.Y.
Tags:
Brokerage
MORE FROM Brokerage
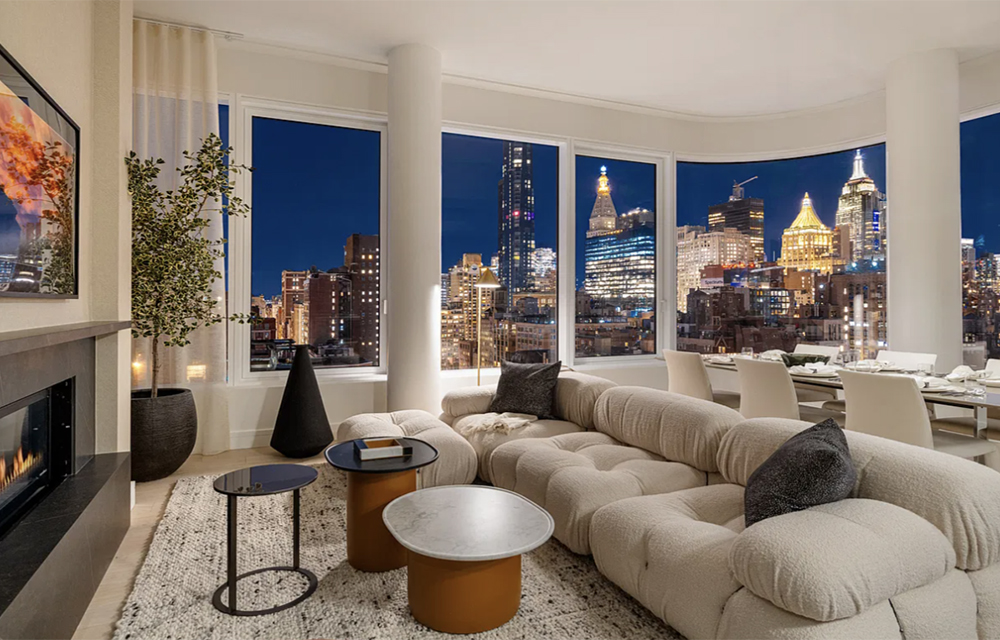
200E20TH sells out in Gramercy, penthouse A closes out sales at the CetraRuddy-designed condominium residences
Manhattan, NY 200E20TH, the CetraRuddy-designed architectural masterwork that brought a curved, contemporary sensibility to Gramercy’s Beaux-Arts streetscape, has
Quick Hits
Columns and Thought Leadership
Hunt commercial real estate question and answer: Fortune 500 wisdom - by David Hunt
Yes, there are lessons to be learned from the largest companies in America when comes to managing your real estate. But the decision to buy or lease real estate may not be one of
Hunt CRE question and answer: Choosing a real estate agent - by David Hunt
First, we will only work with one agent exclusively. The primary reason is that we want that agent to legally represent our client’s interests. In New York State, a real estate agent has a fiduciary
The art of investing in real estate - by Thomas Donovan
Real estate investing is as much an art as it is a skill. No one can time the market, or the factors that drive it, perfectly. Location, zoning, size, transportation, and neighborhood density give you a baseline for
New York’s streets are full again, and the retail numbers prove it - by Noam Aziz
Walk down any New York block this year and you can feel it. The sidewalks are crowded, the storefronts are lit, and the energy that defines this city is back at full volume.
.gif)